October 2, 2026
Short answer: The equity in your current home is usually the down payment on your next one — but it’s locked up until you sell. To trade up, you can access that equity before selling with a HELOC, a cash-out refinance, or a buy-before-you-sell bridge loan. The Knock Bridge Loan™ unlocks up to $1,000,000 of it at 0% interest for up to six months, so you can buy the bigger home first.
Your equity is your buying power — if you can reach it
If you’ve owned your home for a while, you’ve likely built substantial equity. On paper, that’s the down payment for a bigger house. The problem is access: that equity is tied up in the home, and the traditional way to reach it is to sell — which means selling before you buy, temporary housing, and a rushed purchase.
The whole game when trading up is turning that locked equity into usable cash at the right moment, without having to sell first. Do that well and you can shop for the bigger home as a strong buyer. Do it poorly and you either overpay in interest or end up making a weak, contingent offer. It helps to know how much equity you can actually put to work; see putting your home equity to work.
Ways to tap your equity to trade up
There are three common tools, and they behave very differently during the window between buying and selling.
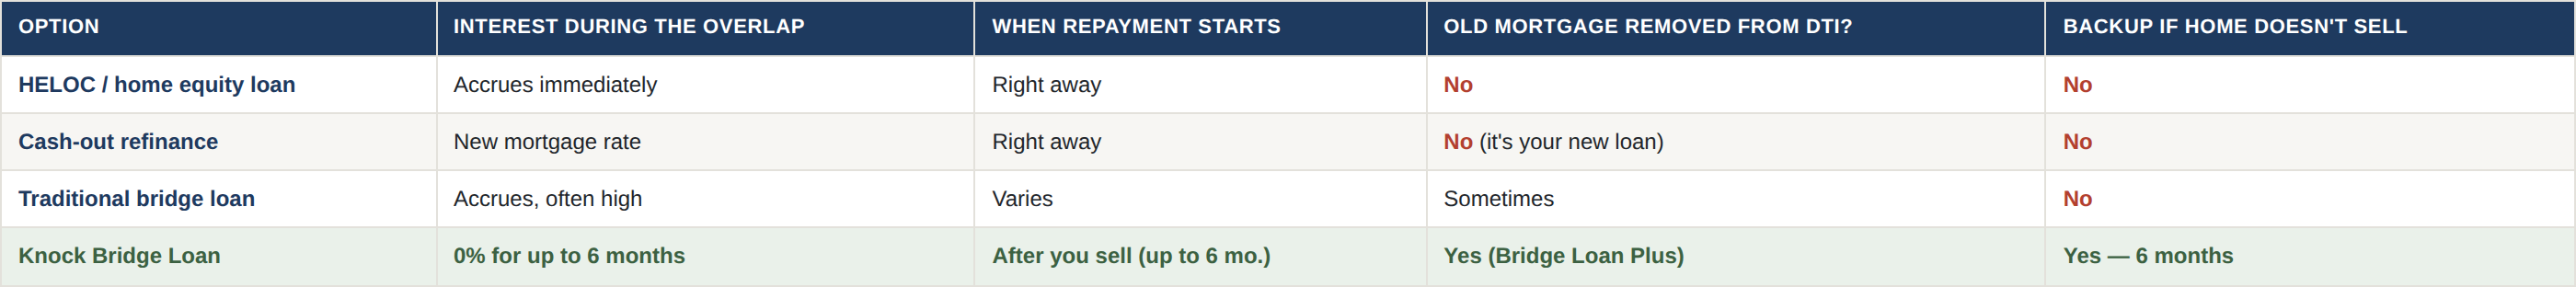
A HELOC or home equity loan lets you borrow against your equity while keeping your current mortgage. It’s flexible, but interest starts accruing immediately, and the new payment plus your existing mortgage both count against your debt-to-income ratio — which can make qualifying for the bigger home harder.
A cash-out refinance replaces your current mortgage with a larger one and hands you the difference in cash. It can work, but you’re refinancing at today’s rates and resetting your loan, and you still carry that mortgage until you sell.
A buy-before-you-sell bridge loan is purpose-built for trading up. The Knock Bridge Loan™ unlocks up to $1,000,000 of equity at 0% interest for up to six months, removes your departing mortgage from your DTI with Bridge Loan Plus, and includes a guaranteed backup offer if your home doesn’t sell. You repay it once your current home sells.
Equity-tapping options, side by side
For a cost breakdown, see what a Knock Bridge Loan costs.
Frequently asked questions
How much of my equity can I use to trade up? Up to $1,000,000 with the Knock Bridge Loan, depending on your available equity. You can put it toward the down payment, buy down your rate, or cover carrying costs on your current home.
Is a HELOC or a bridge loan better for trading up? A HELOC charges interest right away and leaves your old mortgage counting against you. A buy-before-you-sell bridge loan is designed to unlock equity at 0% interest and remove the old mortgage from your DTI — a better fit when the goal is to buy the bigger home first.
When do I pay the equity back? When your current home sells. With the Knock Bridge Loan, repayment doesn’t begin for up to six months, and the loan is repaid from your sale proceeds.
What if my home sells for more than expected? You keep the upside. The guaranteed backup offer is a floor, not a cap — if your home sells for more on the open market, that gain is yours.
Ready to put your equity to work on a bigger home? See how much you can unlock with a Knock Bridge Loan, or learn how the Knock Bridge Loan works.