September 29, 2026
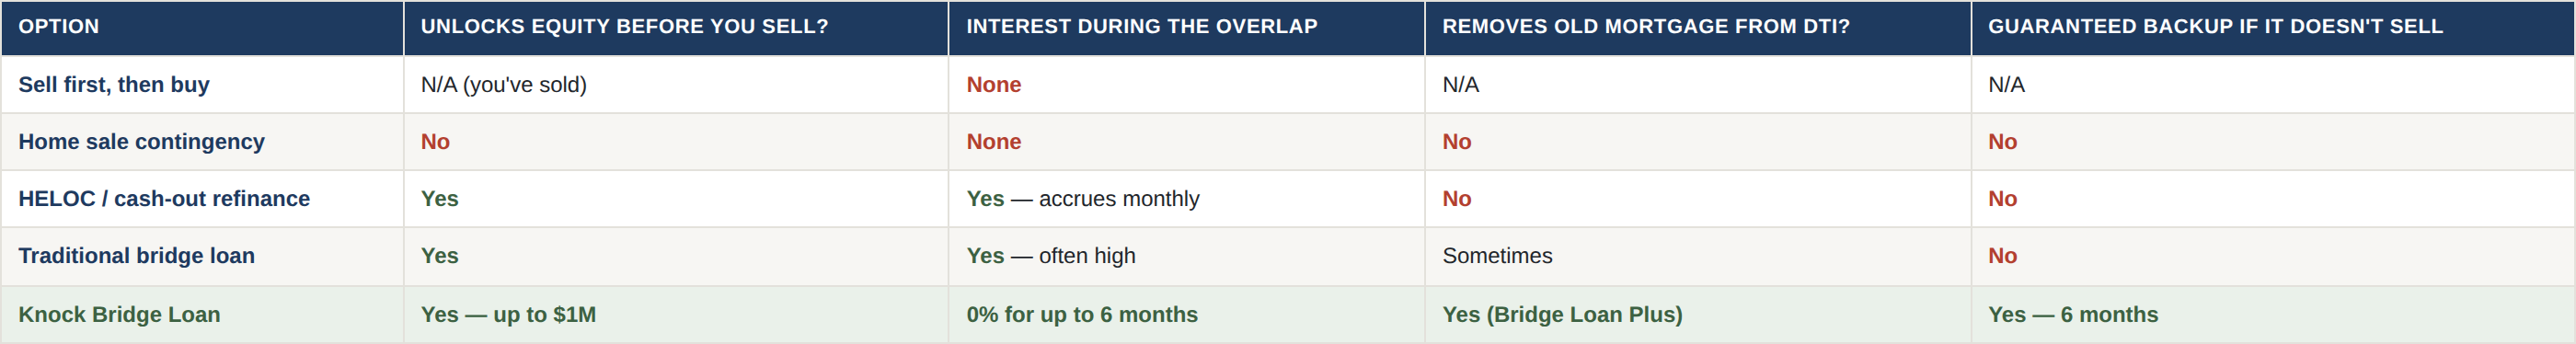
Short answer: Move-up buyers generally have five financing options: sell first and buy with the proceeds, make a home-sale-contingent offer, tap equity with a HELOC or cash-out refinance, use a traditional bridge loan, or use a buy-before-you-sell program like the Knock Bridge Loan™. They differ on whether you can access your equity before selling, whether you carry interest, and whether your old mortgage counts against qualifying.
What makes financing a move-up different
Buying a bigger home when you already own one isn’t the same as being a first-time buyer. Most of your down payment is tied up in your current house, and a lender looking at your application sees your existing mortgage as debt. So the real question isn’t just “can I afford the bigger house” — it’s “how do I turn the equity I already have into a down payment, and qualify without my current mortgage getting in the way?”
The biggest issue is usually liquidity timing, not net worth. You might have $250,000 in equity and still be unable to write a competitive offer if that money is stuck in your current home. The right financing structure turns future sale proceeds into buying power now.
The main financing options, compared
Each option handles the equity and qualification problem differently.
How to choose the right one
If you’re not in a hurry and don’t mind moving twice, selling first is the simplest and cheapest path — you just trade convenience for cost. A home sale contingency keeps your offer cheap but weak, which struggles in a competitive market; see how sellers view contingent offers. A HELOC or cash-out refinance can free up equity, but you start paying interest right away and your old mortgage still counts against your debt-to-income ratio.
A buy-before-you-sell program is designed specifically for the move-up buyer’s problem. The Knock Bridge Loan™ unlocks up to $1,000,000 of equity at 0% interest for up to six months, removes your departing mortgage from your DTI so you can qualify, and includes a guaranteed backup offer. That combination is what lets you shop for the bigger home as a strong, non-contingent buyer without carrying the cost of two mortgages. For who benefits most, see who a bridge loan is best for.
Frequently asked questions
What’s the cheapest way to finance a move-up purchase? Selling first and buying with your proceeds avoids financing costs entirely, but it usually means temporary housing and moving twice. If you want to buy first without paying interest during the overlap, a 0%-interest buy-before-you-sell program is often the most cost-effective way to do it.
Can I use a HELOC to buy a bigger house before selling? You can, but a HELOC accrues interest immediately, and lenders typically still count both your current mortgage and the HELOC against your qualification. Compare that with how the Knock Bridge Loan works.
Will I qualify for the new mortgage while still owning my current home? That depends on your debt-to-income ratio. Removing your departing mortgage from DTI — as Bridge Loan Plus does — is often what makes qualifying possible.
How much does a move-up program cost? It varies by program and home price. See what a Knock Bridge Loan costs for a breakdown of the fees involved.
Comparing your options for a bigger home? See if your home qualifies for a Knock Bridge Loan, or read how to buy a house before selling.