October 1, 2026
Short answer: To avoid two mortgage payments when upsizing, use a buy-before-you-sell program that unlocks your equity at 0% interest and lets you cover your current home’s payments from that equity while it’s on the market. The Knock Bridge Loan™ does this for up to six months, and if your home doesn’t sell, a guaranteed backup offer buys it — so you never pay both mortgages out of pocket.
Where the double payment actually comes from
When you upsize, there’s usually a window where you own both homes at once. You’ve closed on the bigger house, but your old one hasn’t sold yet. During that overlap, both mortgages are technically due — plus taxes, insurance, and utilities on two properties. Carrying that out of pocket is what makes people nervous about upsizing, and it’s a legitimate concern. Recurring debts like your mortgage count toward your obligations, per the Consumer Financial Protection Bureau’s guidance on debt-to-income, which is why lenders and buyers alike take the overlap seriously.
The length of that overlap is the variable that matters most. If your old home sells in three weeks, the double payment is a rounding error. If it takes five months, it can cost real money. The goal is to structure your move so the overlap is both short and — ideally — not paid out of your own pocket.
Three ways to keep the overlap from costing you
You can attack the double-payment problem from three angles, and the strongest approach uses all three at once.
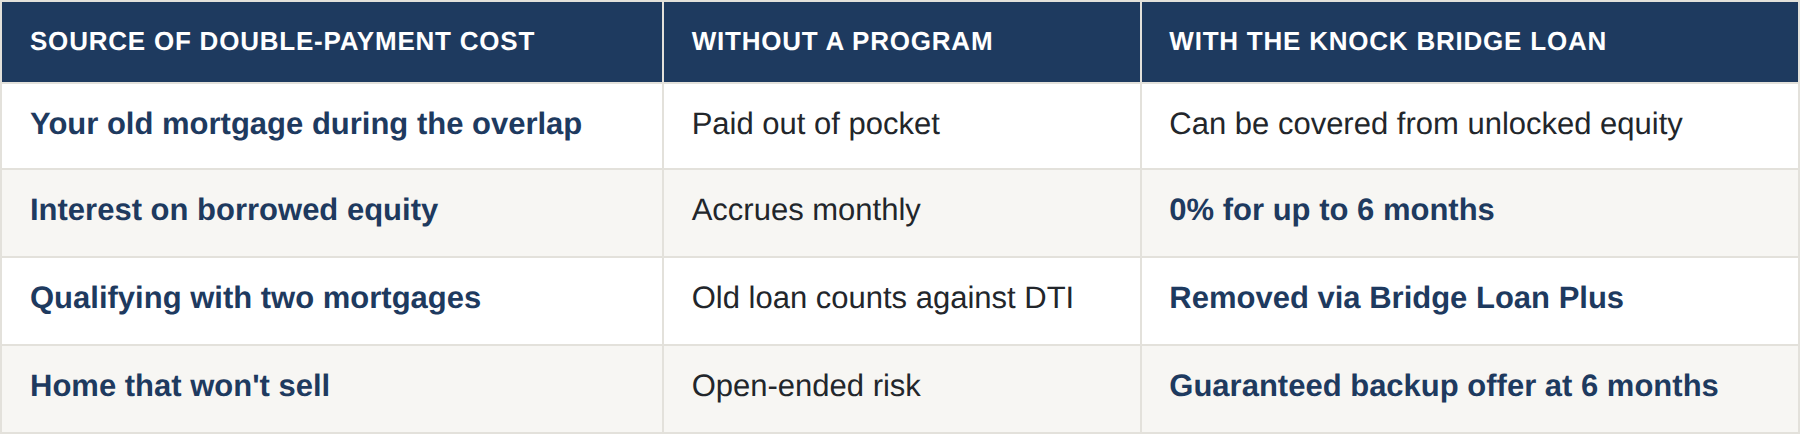
Cover the old payments from your equity. Instead of paying your current mortgage from your checking account during the overlap, you can use part of your unlocked equity to cover it. The Knock Bridge Loan™ lets you draw up to $1,000,000 of equity at 0% interest and use a portion to cover up to six months of payments on your departing home.
Don’t pay interest on the bridge. A traditional bridge loan or HELOC charges interest from day one, which quietly adds to your carrying cost. Knock’s bridge is 0% interest for up to six months, so the overlap doesn’t compound.
Cap the downside with a guaranteed offer. The scariest version of the double payment is the one with no end date — the home that just won’t sell. The guaranteed Knock Purchase Offer removes that fear: if your home doesn’t sell within six months, Knock buys it at a price agreed upfront. For more on that risk, see what happens if your old house doesn’t sell.
What drives the overlap cost — and how each is handled
Frequently asked questions
How long will I really own two homes? It depends on your local market and pricing. Many homes sell quickly when priced right, but the safe way to plan is to assume the overlap could last a few months and structure your financing so you’re not paying both mortgages yourself during that time.
Can I avoid the overlap entirely? Only by selling first, which usually means temporary housing and moving twice. Buying first with a program removes the out-of-pocket double payment without forcing a double move.
Does my current mortgage stop me from qualifying for the new one? It can, because it counts toward your debt-to-income ratio. Bridge Loan Plus removes the departing mortgage from that calculation so you can qualify.
What if I’ve already found the bigger home? You can move forward now — unlock your equity, make a non-contingent offer, and list your current home after you’ve moved.
Want to upsize without doubling up on payments? See if your home qualifies for a Knock Bridge Loan, or compare bridge loan vs. contingency costs.