September 28, 2026
Short answer: You can move up to a bigger home without carrying two mortgages by using your current home’s equity to buy first, then selling. A program like the Knock Bridge Loan™ unlocks that equity at 0% interest for up to six months, removes your old mortgage from your debt-to-income ratio so you can qualify, and can cover your old payments until the home sells — so you’re not paying two mortgages out of pocket.
Why moving up creates the “two mortgage” problem
When you already own a home, upgrading to a bigger one runs into a timing trap. Your down payment is locked inside your current house, and you can’t easily get it out until you sell. But to buy the bigger home first, you’d normally need to qualify while still carrying your existing mortgage — and then keep paying both loans until the old one closes.
That’s the squeeze move-up buyers feel: two mortgage payments at once, a down payment you can’t reach, and a lender counting your current mortgage against you. Owning two homes at the same time can be a real financial strain, which is exactly why buying before selling scares people off. The good news is that the overlap is a solvable problem, not a reason to give up on the bigger house.
How to buy the bigger home first without two out-of-pocket payments
The fix is a financing structure that turns your future sale proceeds into buying power now. Instead of waiting for your old home to sell, you unlock its equity up front, use it for the new down payment, and repay it once the sale closes. Three things have to line up for this to work cleanly: you need access to your equity before selling, your lender needs to stop counting the old mortgage against your qualification, and you need a way to cover the old payment during the overlap.
The Knock Bridge Loan™ is built around exactly that. It lends you up to $1,000,000 of your equity at 0% interest for up to six months, so you can make a strong, non-contingent offer on the bigger home. With Bridge Loan Plus, your departing mortgage is removed from your debt-to-income ratio, so you can qualify for the new loan without the old payment dragging you down. You can even use part of the loan to cover up to six months of payments on your current home while it’s on the market — meaning you’re not paying two mortgages out of pocket. And if your home doesn’t sell within six months, the guaranteed Knock Purchase Offer buys it at a price agreed upfront, so you’re never stuck with two houses.
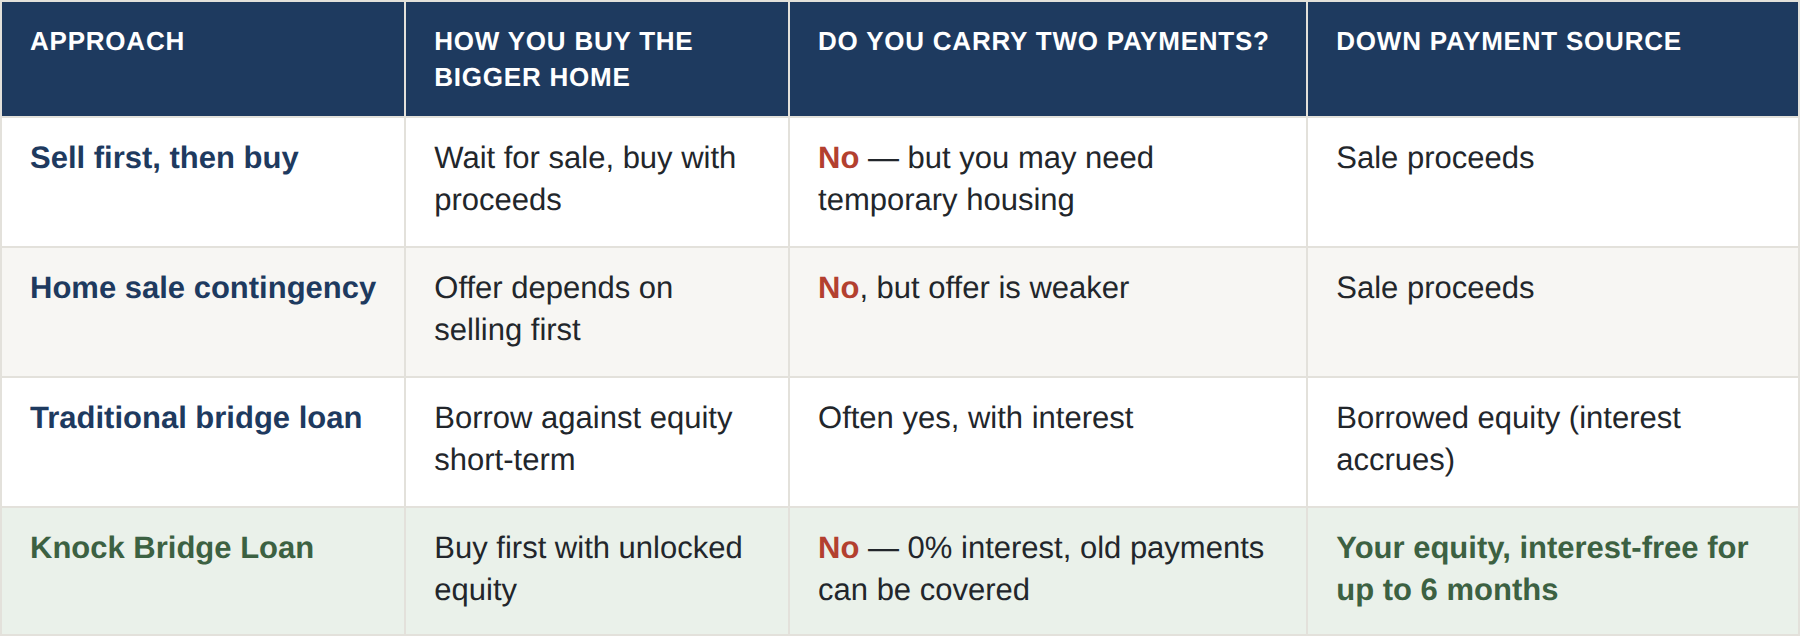
Four ways to move up — and what each does with the second mortgage
Not every path avoids the double payment. Here’s how the common approaches compare for a move-up buyer.
For a deeper look at how these structures differ on cost, see Bridge Loan vs. Home Sale Contingency: Costs and Timeline.
Frequently asked questions
Can I qualify for a bigger mortgage if I still own my current home? Often yes. The obstacle is usually your debt-to-income ratio, because lenders count your existing mortgage. Programs like Bridge Loan Plus remove your departing mortgage from that calculation, so you can qualify based on the new loan alone. See how lenders handle buyers who haven’t sold yet.
Do I have to pay two mortgages while my old home is on the market? Not necessarily. With the Knock Bridge Loan, you can use part of your unlocked equity to cover up to six months of payments on your current home, so you’re not paying both out of pocket during the overlap.
What if my current home doesn’t sell? The guaranteed Knock Purchase Offer acts as a backstop — if your home doesn’t sell within six months, Knock buys it at a price set upfront, and you keep any upside if it sells for more on the open market.
How much of my equity can I use? Up to $1,000,000, depending on your available equity. You can put it toward the down payment, buy down your rate, or cover carrying costs.
Ready to move up without doubling your mortgage payments? See if your home qualifies for a Knock Bridge Loan, or read the complete guide to buying before you sell.