September 30, 2026
Short answer: Yes. You can buy a bigger house before selling your current one by unlocking your existing equity for the down payment and qualifying with your old mortgage removed from your debt-to-income ratio. A program like the Knock Bridge Loan™ makes this possible with 0% interest for up to six months and a guaranteed backup offer, so you can buy first and sell on your own timeline.
Is it actually possible — or just risky?
It’s possible, and it’s more common than most move-up buyers realize. The instinct is to sell first because buying first sounds risky: two mortgages, a down payment you can’t reach, and the fear your old home won’t sell. Those are real concerns, but each one has a solution built into modern buy-before-you-sell financing.
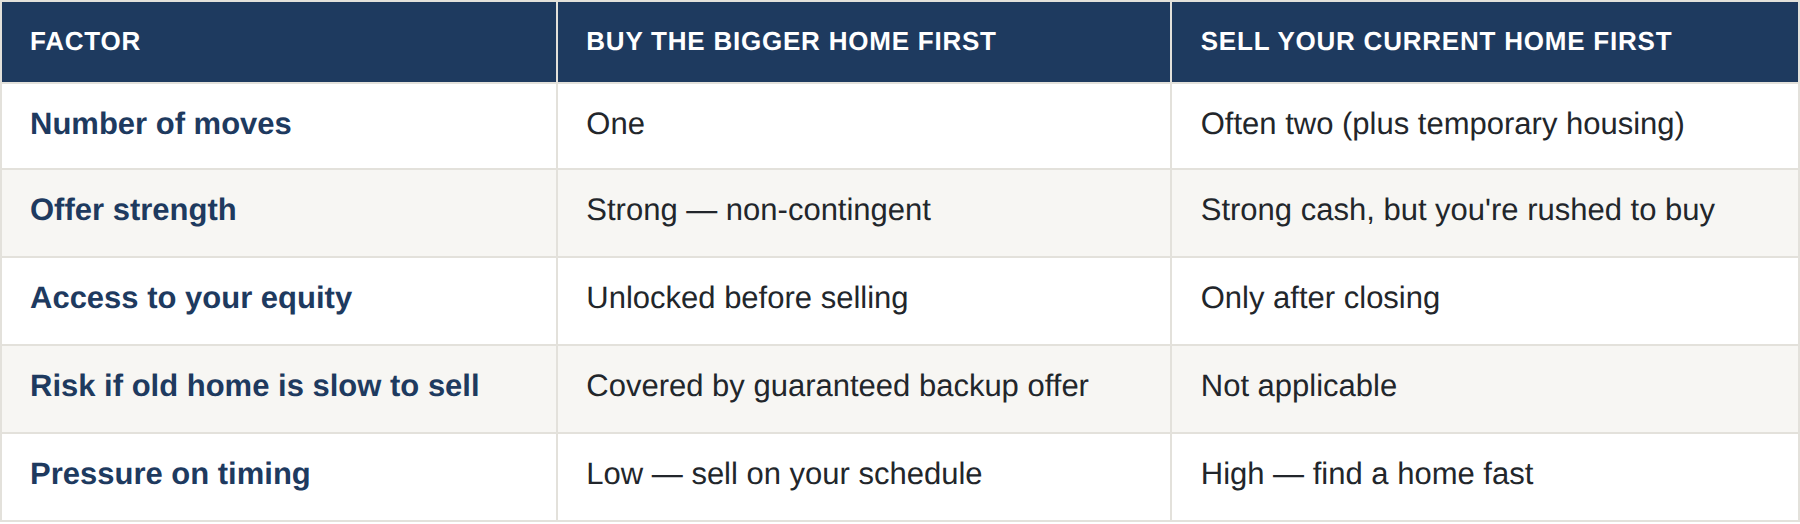
Buying first has real advantages. You move once instead of twice, you shop for the bigger home without the pressure of a ticking clock, and you make a stronger offer because it isn’t contingent on selling your current place. Sellers strongly prefer offers that aren’t tied to another sale — see how to beat the competition with a non-contingent offer.
What it takes to buy the bigger home first
Three things have to be in place before you can comfortably buy before selling: access to your down payment, the ability to qualify, and a safety net.
First, your down payment. It’s sitting in your current home as equity, so you need a way to unlock it before the sale closes. The Knock Bridge Loan™ lends you up to $1,000,000 of that equity at 0% interest for up to six months, which you put toward the bigger home.
Second, qualification. Lenders normally count your existing mortgage against your debt-to-income ratio, which can push you over the limit. Bridge Loan Plus removes that departing mortgage from the calculation so you can qualify for the new loan. More on this in how lenders handle buyers who haven’t sold yet.
Third, a safety net. If your current home doesn’t sell within six months, the guaranteed Knock Purchase Offer buys it at a price agreed upfront — so buying first never leaves you stuck with two houses.
Buy first vs. sell first
For the full process end to end, see the complete guide to buying before you sell and the buy-before-you-sell timeline.
Frequently asked questions
Do I need to sell my current home to get the down payment for a bigger one? No. You can unlock your existing equity before selling and use it for the new down payment, then repay it once your current home sells.
Will buying first mean two mortgage payments? Not necessarily out of pocket. With the Knock Bridge Loan, you can use part of your unlocked equity to cover up to six months of payments on your current home while it’s listed.
Is a non-contingent offer really stronger? Yes. Sellers prefer offers that don’t depend on you selling another home first. See making an offer without a sale contingency.
What happens if the bigger house comes along before I’ve even listed mine? That’s the scenario buy-before-you-sell is built for — you can make the offer now and list your current home after you’ve moved.
Found the bigger home already? See if your current home qualifies for a Knock Bridge Loan, or review the steps to buy a house before selling.